Master Your FAFSA Student Aid Report: A Simple Step-by-Step Guide
Imagine sitting at your kitchen table late at night with a lukewarm cup of coffee. You open an email from the federal student aid office, click the official link, and stare at a page filled with strange numbers, weird codes, and confusing terms.
Your heart sinks a little bit because this single document holds the key to your college future. You wonder if you made a mistake on your income figures or if you missed a deadline.
When I opened my very first financial aid summary years ago, my stomach dropped into a complete knot. I remember staring at the confusing codes and numbers on my laptop screen, convinced that a simple mistake on my form had ruined my chances of paying for college. It took me weeks of stressful phone calls and late-night research to figure out what those numbers actually meant, and I wrote this guide so you never have to feel that same overwhelming panic.
The stress builds up quickly when you realize you do not know whether the big number on the screen means you get thousands of dollars or nothing at all. You just want a straight answer about how much money you will get for school.
Instead, you get legal jargon, mysterious acronyms, and vague instructions that leave you feeling lost. You are not alone in this struggle. Millions of students and parents feel this exact same frustration every single year when trying to make sense of their official aid summary.
What Is the FAFSA Student Aid Report and Why Does It Matter?
Let us break this down into clear, plain English so you can take a deep breath. Your FAFSA Student Aid Report is simply an official summary of all the information you submitted on your aid application.
Think of it like a receipt from a grocery store. When you buy groceries, the receipt shows everything you put in your cart, the prices, and the total cost.
Your aid summary does something very similar for your college application. It records your family income, assets, household size, and school choices.
The federal government processes your form and generates this document to show you what they calculated. It is not your final bill, and it is not your actual financial aid award letter from a college.
Instead, it is the foundational document that colleges use to figure out your eligibility for grants, work-study programs, and loans. If the information on this report is wrong, your final aid offer will also be wrong.
That is why reviewing this document carefully is one of the most important steps in your college funding process. Let us walk through how this form works and what you need to check first.
Decoding the Core Numbers on Your Summary
When you open your document, your eyes will naturally jump to the top of the first page. You will see a few critical numbers that dictate your financial aid status.
The Student Aid Index (SAI)
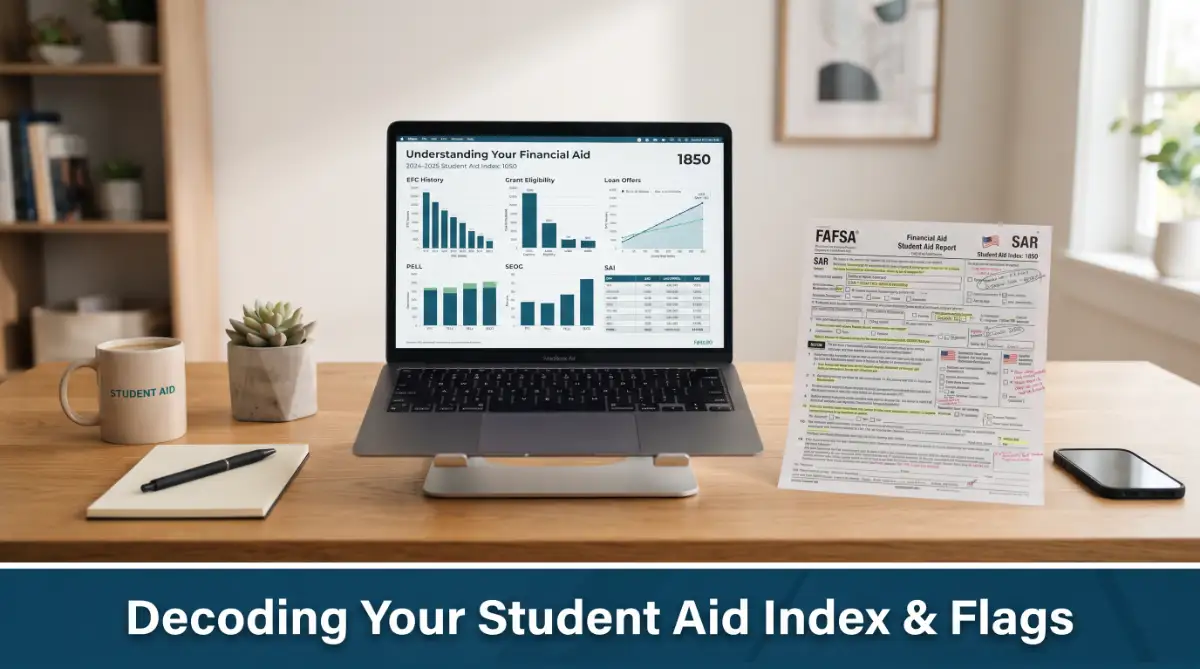
The most prominent number on your summary is your Student Aid Index. This number replaces the old formula known as the Expected Family Contribution.
Many parents see a number like 0500 or 1200 and panic because they think it means they must pay that exact dollar amount immediately. That is a huge misconception.
Your Student Aid Index is simply an index number that colleges use to calculate your financial need. It can range from negative numbers like -1500 up to high positive numbers.
- A negative or zero index: Shows that you have high financial need, making you eligible for maximum grant money.
- A higher positive index: Indicates lower calculated financial need, though you can still qualify for merit aid and unsubsidized loans.
Colleges subtract your index number from their total Cost of Attendance to decide how much aid you need.
Key Parts of Your Report You Cannot Ignore
Your official aid report is broken down into four major sections. Understanding what lives in each section makes reviewing the document much faster and less scary.
Section 1: Application Processing Results
This section gives you an immediate status update on your application. It tells you if your form was successfully processed or if it was rejected due to missing signatures.
If you see a bold alert message here, read it right away. A rejected form means no college can build your financial aid package.
Look for clear statements confirming that your application went through processing without any systemic errors.
Section 2: Financial Aid Eligibility Overview
This is where you get your first peek at potential federal grant money and loan eligibility. It gives you estimated figures based on full-time college enrollment.
It will tell you if you appear eligible for the Federal Pell Grant, which is money for college that you usually do not have to pay back.
It will also list your eligibility for federal direct loans, showing the maximum amounts you can borrow for your upcoming school term.
Section 3: Data Release and College Choices
This section lists all the colleges you selected to receive your financial aid information. Each school listed here gets a digital copy of your report automatically.
If you decided to apply to a new college last week and do not see it on this list, you must add it manually. Colleges cannot offer you money if they are not listed on your report.
Double-check school codes to ensure you sent your data to the right campus branch.
Section 4: Your Detailed Financial Inputs
The largest part of the report lists every single answer you provided on your original application. It includes your reported tax information, asset values, and family size.
You need to scan these lines to make sure your typing errors did not mess up your figures. A misplaced decimal point can change an income of $40,000 into $400,000 in the system!
Uncovering Common Red Flags and Asterisks
Sometimes, you will notice a strange symbol next to your numbers on the summary page. The most common symbol is a small asterisk or a letter code like "C" next to your Student Aid Index.
What Does the Verification Flag Mean?
If you see an asterisk next to your index number, your application was chosen for a process called verification.
Do not panic if this happens to you. Getting picked for verification does not mean you lied or cheated on your form.
The federal system randomly selects a percentage of applications every year to double-check data accuracy. In other cases, it triggers if your reported income numbers look inconsistent.
When flagged, your college financial aid office will contact you directly to ask for extra documents. They might request tax transcripts, verification worksheets, or proof of identity.
Resolving Data Mismatches Quickly
If your form has a "C" flag, it means there is a mismatch between your form and federal databases. This often happens because of simple spelling errors or incorrect Social Security numbers.
Here are the most frequent reasons for a data mismatch flag:
- Name discrepancies: Your name on the FAFSA does not match your official Social Security card.
- Selective service or citizenship issues: The system could not verify your citizenship status with federal records.
- Unresolved drug convictions or loan default status: Prior federal loan issues are blocking your current eligibility.
To fix a mismatch, log into your portal, view the specific error code explanation, and follow the simple steps to correct your personal profile.
Step-by-Step Guide to Fixing Mistakes on Your Report
Finding an error on your aid summary can be stressful, but fixing it is straightforward once you know where to click. Follow this logical sequence to correct your information quickly.
Watch this quick step-by-step video walkthrough to see exactly how to navigate your online portal and fix errors on your aid report in real time! After watching the short clip, continue reading the practical guide below to learn advanced strategies for appealing your aid package.
Step 1: Gather Your Reference Documents
Before you press any buttons to edit your report, get all your original tax documents, bank statements, and personal ID cards in front of you.
Having your W-2 forms and tax returns on hand keeps you from guessing numbers a second time. Accuracy is far more important than speed here.
Step 2: Log In to the Official Federal Portal
Go directly to the official federal student aid website and sign in using your account username and password.
Once logged in, click on your active application dashboard and select the option to view your submission summary.
Step 3: Select "Make Corrections"
Look for the button that allows you to make edits or updates to your existing summary.
The system will unlock the fields, allowing you to edit numbers, change personal details, or add new college codes to your distribution list.
Step 4: Double-Check Taxes and Asset Numbers
Carefully correct the wrong entries. If you transferred your tax data directly from the IRS data tool, try not to change those fields manually unless requested.
I learned this lesson the hard way when I accidentally listed my family's primary home equity in the general asset box, which artificially drove up my calculated index number. Once I caught the error, called my school's aid office, and submitted a quick online correction, my index dropped significantly and unlocked thousands of dollars in grant aid that I almost missed out on entirely.
Direct tax transfers are considered verified and greatly reduce your chances of getting flagged for review later.
Step 5: Resign and Resubmit
Both you and your parent (if you are a dependent student) must sign the updated form with your digital IDs.
Once you hit submit, wait a few days for the system to process the changes and generate a fresh summary.
Common Myths About the FAFSA Aid Report
There is a massive amount of bad advice circulating online regarding student aid reports. Let us clear up the most dangerous myths so you can protect your financial future.
Myth 1: "A High Student Aid Index Means I Get Zero Financial Aid"
Many families assume that if their calculated index number is high, completing the FAFSA was a total waste of time. This is completely wrong.
Even families with high index numbers can receive merit-based scholarships, work-study positions, and non-need-based federal loans.
Furthermore, many private scholarship programs require a completed aid summary on file before they will award money, regardless of family income.
Myth 2: "My Aid Report Is the Final Financial Offer From My School"
It is easy to look at the grant estimates on your report and assume that is your final college package.
Your summary only shows potential eligibility for federal aid programs. It does not include state grants, institutional scholarships, or tuition discounts offered directly by your chosen university.
You must wait for the official Financial Aid Award Letter directly from each college's financial aid office to see your actual net cost.
Myth 3: "I Cannot Change My Report After Submitting It"
Some students believe that once their summary is processed, their financial situation is locked in stone forever.
If your family experiences a major life event—like a job loss, medical emergency, or divorce—you can request a formal review.
You will need to contact your college financial aid office directly to request a Special Circumstances Appeal. They have the authority to adjust your aid numbers based on real-world changes.
Pro Tips for Managing Your Aid Summary Like a Pro
Managing your financial aid step-by-step takes organization, patience, and attention to detail. Here are practical tips to keep you ahead of the game.
Expert Insight Box:
Create a dedicated folder on your computer titled "College Aid [Current Year]". Save a downloaded PDF copy of every version of your Student Aid Report, along with timestamps and confirmation receipts. Financial aid offices occasionally lose digital records, and having your own dated copies gives you instant proof of submission.
Keep Track of Key Deadlines
Federal deadlines, state deadlines, and individual college deadlines are all completely different dates.
State aid programs often run out of money quickly, operating on a first-come, first-served basis.
Submitting and reviewing your aid summary early gives you the best chance at securing available state and institutional grant dollars.
Communicate With College Financial Aid Officers
Do not be afraid to pick up the phone and call the financial aid office at your top-choice university.
Financial aid counselors are real human beings whose entire job is helping students navigate this exact paper trail.
If you do not understand a specific error code or verification message on your summary, ask them directly. They can look up your record in their system and tell you precisely what documents they need from you.
Comparing Aid Summary Data With Actual Award Letters
Once your aid report is processed cleanly, the data flows out to your chosen colleges. A few weeks later, those colleges send you official financial aid award notifications.
Here is how your aid summary directly influences the award letter you receive from a university:
Calculating Your True Net Price
When you receive your financial aid award letters, compare them against the cost of attendance listed on your aid summary.
Use this simple math formula to find your actual out-of-pocket cost for each school:
Notice that we do not subtract loans from the cost when calculating net price. Loans are debt that you must pay back later, not discount money given to you.
Focus heavily on maximizing your gift aid while keeping your total student debt as low as humanly possible.
Essential Terminology Glossary
To help you scan your report with total confidence, here is a quick reference guide to the standard terms you will see on the pages of your document:
- Student Aid Index (SAI): The formula-based number used by colleges to determine your total financial aid eligibility.
- Cost of Attendance (COA): The total estimated price tag of attending a college for one academic year, including tuition, housing, books, and living expenses.
- Financial Need: The gap between a college's Cost of Attendance and your calculated Student Aid Index.
- Federal Pell Grant: Federal financial aid awarded to undergraduate students with significant financial need that does not require repayment.
- Direct Subsidized Loan: A federal student loan where the government pays the interest while you are enrolled in school at least half-time.
- Direct Unsubsidized Loan: A federal loan where interest starts accumulating immediately from the day the money is sent to your school.
- Verification: An administrative review process where a college requests official paperwork to confirm the financial figures reported on your form.
- Master Promissory Note (MPN): A legal contract you must sign before receiving federal loans, promising to pay back the borrowed funds plus interest.
Action Plan: What to Do Right Now
Now that you know how to read and understand your student aid summary, take these immediate actions to keep your college plans on track:
- Log in to your portal: Download and print a clean PDF copy of your latest submission summary.
- Scan Section 1: Verify that your processing status reads as complete with no system rejections.
- Check for flags: Look for asterisks or letter codes next to your Student Aid Index number.
- Audit your financial figures: Review your tax and asset numbers line by line to spot any obvious typing mistakes.
- Confirm your college list: Ensure every single university you applied to is listed in Section 3 of your report.
- Submit required verification forms: If selected for review, send all requested tax transcripts to your college's financial aid office immediately.
Taking thirty minutes today to carefully review your report saves you from massive financial stress later. Stay organized, keep track of your paperwork, and advocate for yourself every step of the way toward your college degree.
Unlocking Hidden Value: Advanced Strategies for Your Aid Summary
Reviewing your initial financial report is only the beginning of your funding journey. Once you understand the basic numbers, you can use advanced strategies to optimize your financial position before your college bill arrives.
Many families accept their initial aid figures without realizing that the federal processing system only captures a flat snapshot of your financial life. You have legal tools and administrative rights to present a fuller picture of your financial situation.
Requesting Professional Judgment Reviews
College financial aid officers have special legal authority granted by the federal government. This authority, known as Professional Judgment, allows them to manually adjust your Student Aid Index if your official summary does not reflect your current reality.
If your household experienced a major financial shock after filing your tax forms, your processed report is essentially out of date. Common reasons for a review include sudden job loss, high medical bills not covered by insurance, or the death of a primary breadwinner.
To start this process, do not simply send an angry email complaining about your offer. Write a clear, polite letter detailing your exact financial change and attach objective proof, such as medical receipts or termination notices.
You can read the official guidelines on Professional Judgment regulations at Federal Student Aid to understand what documentation counselors require before altering your record.
Strategic Asset Placement and Reporting
Understanding which assets must be reported on your application protects you from inflating your index number unnecessarily. The federal formula specifically excludes certain types of personal wealth from its calculation.
Your primary residence—the home you live in every day—does not get counted as an asset on your main federal form. Neither do tax-advantaged retirement accounts like traditional 401(k) plans or IRA accounts.
If you reported retirement savings or home equity in the general asset fields by mistake, your calculated need will look much smaller than it actually is. Correcting these entries immediately lowers your index number, which opens up more grant funding.
Always check whether cash in your checking account is committed to immediate household expenses before filing an updated report. Paying off credit card bills or necessary home repairs before reporting your cash balances is a smart, legal way to reflect true liquidity.
Navigating Multiple Students in College
In past years, having multiple family members in college at the same time provided an automatic discount on your calculated family contribution. Recent updates to federal formulas changed how multiple enrollments are handled on paper.
While the federal baseline formula no longer automatically divides your index number by the number of students enrolled, individual colleges still care deeply about this burden. Many private institutions use their own aid money to assist families supporting two or more undergraduates simultaneously.
When you send your summary to your prospective colleges, attach a separate letter informing them of siblings enrolled in higher education. Ask the financial aid office if they offer institutional scholarships specifically designed to offset double-tuition households.
Real-Life Scenario: The One-Time Financial Spike
Consider the story of Sarah and her daughter, Maya. During the tax year used for Maya's aid report, Sarah sold a small piece of inherited land to pay off pressing family debt.
This sale created a one-time surge in Sarah's reported income on paper, making her look wealthy to the federal automated system. Consequently, Maya's aid summary came back with an extremely high index number, qualifying her for zero grant aid.
Instead of giving up on college, Sarah contacted the university financial aid director. She provided tax records proving the land sale was a single, non-recurring event that would not happen again.
The financial aid counselor approved a professional adjustment, removing the one-time income spike from the calculation. Maya received $6,500 in additional institutional grant money for her upcoming freshman term.

Devastating Errors That Silently Rob Students of College Grants
Small errors on your student aid report can lead to massive financial losses. Understanding these common traps helps you safeguard your funding and prevent sudden processing freezes.
When panic sets in, families often make quick edits without double-checking the facts. Taking a systematic approach to reading your paperwork prevents costly multi-year mistakes.
Misunderstanding Parental Contributions in Changed Household Structures
Family dynamic shifts can create massive confusion when deciding whose financial information belongs on your aid form. Reporting the wrong parent's income is one of the quickest ways to trigger an official audit.
For dependent students whose parents are separated or divorced, federal rules require you to report the parent who provides the greater portion of your financial support. This is not always the parent who claims you as a dependent on income tax filings.
When parents experience a marital split later in life, asset reporting becomes even more complex. If your family is adjusting to navigating gray divorce and family adaptation, identifying which parent acts as the primary contributor on your aid summary requires extra attention.
Furthermore, if the primary supporting parent has remarried, the step-parent's income must also be included on the form. Leaving off a step-parent's income triggers automatic tax verification flags that delay your entire application.
In addition, financial gifts or living support from non-custodial relatives or grandparents can alter your income landscape if reported incorrectly. Learning how to maintain connections with your grandchildren post divorce while keeping cash support structured cleanly ensures your aid files stay clear of unexpected flags.
The Danger of Ignoring Application Deadlines
Many families assume that as long as they complete their forms before college starts in the autumn, they are completely safe. This single misunderstanding costs students millions of dollars in available grant money every single term.
Financial aid operates on several distinct layers of deadlines:
- Federal Deadlines: The final cutoff date to receive federal aid for an academic cycle.
- State Deadlines: Strict, early dates set by state governments to distribute state-specific grants.
- Institutional Deadlines: Early priority cutoffs set by individual colleges to hand out their own scholarship money.
State and institutional funds are limited and usually operate on a first-come, first-served basis. If your aid summary processed cleanly in April, but your state deadline was March 1st, you permanently lose access to free state grant money.
You can review published financial aid research and policy summaries at the National Association of Student Financial Aid Administrators to see how early filing impacts grant allocation rates across different demographic groups.
Typing Errors in Social Security Numbers and Names
A simple typo in your name or date of birth can freeze your application for weeks. The federal processing system cross-checks your application details directly against Social Security Administration databases.
If you use a nickname on your form instead of your legal name as printed on your Social Security card, the database match will fail. The system puts a hold on your summary until you present physical verification documents to your school.
Always check that the names, Social Security numbers, and birth dates for both student and parents match official government records word-for-word.
Reporting Business and Real Estate Assets Incorrectly
Understanding how to classify small businesses and real estate assets on your form requires extreme care. Recent updates to federal law altered how small family businesses are evaluated in aid calculations.
If your family owns a small business or family farm, you must report the net value of those business assets unless you meet specific exemption thresholds. Net value means the current market value of the business minus any debts secured directly by that property.
Reporting the total gross value of a business instead of its net worth makes your family look much wealthier than it actually is. Always subtract business debts from asset values before entering numbers into your form fields.
Similarly, rental properties must be reported as real estate investment assets, not as primary homes. Mixing up residential property with investment holdings inflates your calculated wealth and reduces your need-based grant offers.
Your Blueprint for Securing Maximum College Funding
Navigating student aid summaries does not have to feel like an impossible puzzle. When you approach the process with a clear plan, you turn a confusing government document into a practical tool for funding your education.
Your Student Aid Report is simply a communication tool between you, the federal government, and your chosen universities. You now possess the exact knowledge needed to review every line, spot errors, and correct mistakes before they harm your wallet.
Your Immediate Action Plan
To ensure you get every dollar of financial aid you deserve, take these concrete steps over the coming days:
- Download your full summary: Keep a clean digital copy stored in a safe folder on your personal computer.
- Audit your personal details: Ensure names, Social Security numbers, and address details match your legal documents.
- Verify asset numbers: Confirm that retirement accounts, home equity, and gross business values were not reported accidentally.
- Check for verification codes: Look for asterisks or letter warnings next to your calculated index number.
- Contact financial aid offices: Reach out to your college counselors early if your family experienced job loss or major medical costs.
The Path Forward
Education is one of the most valuable investments you will ever make in yourself or your children. Do not let complicated paperwork or confusing government acronyms stand between you and your college goals.
Take control of your aid summary today, ask questions when you feel uncertain, and hold your head high. You have the tools, the knowledge, and the power to secure the financial aid package you need to succeed.
Looking back, taking thirty minutes to review my own aid report line by line was the single best financial move I made before stepping onto a college campus. Do not let fear or technical jargon keep you from getting the college funding you truly earn—take charge of your paperwork today and secure your financial future!
Disclaimer
This educational guide is provided strictly for informational and educational purposes. It does not constitute formal financial, legal, or tax advice. Financial aid regulations, eligibility formulas, and institutional policies change frequently. Always consult directly with an accredited college financial aid counselor or a qualified financial planner to discuss your family's specific financial situation before making major college funding decisions.